All Categories
Featured
Managing Life Insurance for Modern Diabetic Applicants
2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips
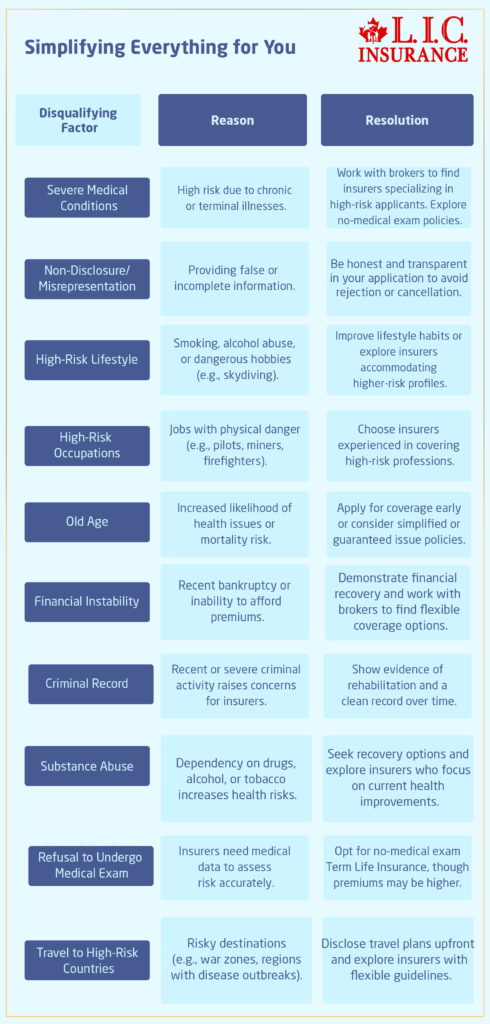

2026 Innovations in Impaired Risk Insurance Markets
Table of Contents
Why you can trust Quality Verified At, we are committed to offering the prompt, precise and professional information customers need to make wise insurance coverage decisions. All our content is composed and evaluated by market specialists and insurance experts. Our group thoroughly vets our rate information to guarantee we just offer reliable and up-to-date insurance pricing.
We follow the greatest editorial standards. Our content is based entirely on unbiased research and data gathering. We keep stringent editorial self-reliance to guarantee objective coverage of the insurance coverage market. If you have actually recently been identified with cancer or have a history of cancer, your eligibility for life insurance becomes complicated.
Cancer clients just qualify for an ensured life insurance policy with minimal protection and limited payments during the preliminary years. Cancer survivors who recovered and have been in remission for at least 5 years can get a standard term or permanent life insurance policy, depending on the severity of their medical diagnosis.
Last cost insurance offers a typically low amount of coverage however still provides funds to cover medical costs or a funeral. If you're in remission, then insurers might provide you traditional protection, however it depends upon a few factors: The date you were identified The type of cancer you had The stage of cancer you had Your treatment history Before they underwrite a policy, many insurers will utilize guidelines from the National Cancer Institute's "Security, Epidemiology, and Outcome" (SEER) database.
Insurers will use this details, as well as specifics about your specific case and diagnosis to identify what type of policy you certify for or if you qualify at all. Some life insurance business may be reluctant to offer protection for somebody with a history of cancer, however there are plenty of others who are ready to do so.

Steps for Lowering Premiums With Chronic Illnesses
Make certain to get quotes from multiple business so that you can compare rates and coverage alternatives. Last cost life insurance policies are usually more costly than other policies and do not need a medical examination or health questions. This makes them perfect for individuals with pre-existing conditions like cancer.
Life Insurance for Cancer SurvivorsThe trade-off with final cost insurance is that the policy amounts are relatively low compared to conventional life insurance coverage. Usually, a final expenditure policy may have a stated value that ranges from $5,000 to $50,000. There are two kinds of final expense insurance coverage: Simplified concern term insurance coverage is a type of life insurance coverage that supplies insurance coverage quickly.
To get a streamlined life insurance coverage policy, you just need to respond to a few medical questions. Another option is an ensured concern policy, which does not involve any medical questions. You also can get a policy with a graded death benefit. If you receive a policy, insurance companies will use various ratings to determine your premium.
For example, if you have a more tough diagnosis, an insurer may classify you as substandard. This could result in either being rejected protection or only qualifying for a significantly more expensive policy, even if you have a more favorable prognosis or the cancer is in its early phases. However, being identified with particular cancers really may not hurt your chances of getting a policy.
Securing Affordable Coverage for Remission
Each life insurance coverage company has its own requirements for coverage, so while some might provide you a policy, others might not. That's why it's crucial to compare choices and shop around to find the very best suitable for your circumstance. Furthermore, it's a great idea to work with a life insurance coverage representative if you have a history of cancer.
Life Insurance for Cancer SurvivorsA skilled representative understands which insurance providers are more accommodating to your specific medical history, ensuring you get the best rates and protection possible. If you're rejected protection due to a cancer medical diagnosis, you might have the ability to get life insurance coverage through your company's group life insurance coverage plan. The protection limits on these policies are typically lower.

Latest Posts

Managing Life Insurance for Modern Diabetic Applicants
2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips