All Categories
Featured
Managing Life Insurance for Modern Diabetic Applicants
2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips
Life Insurance Strategies for Disabled Trusts
Table of Contents
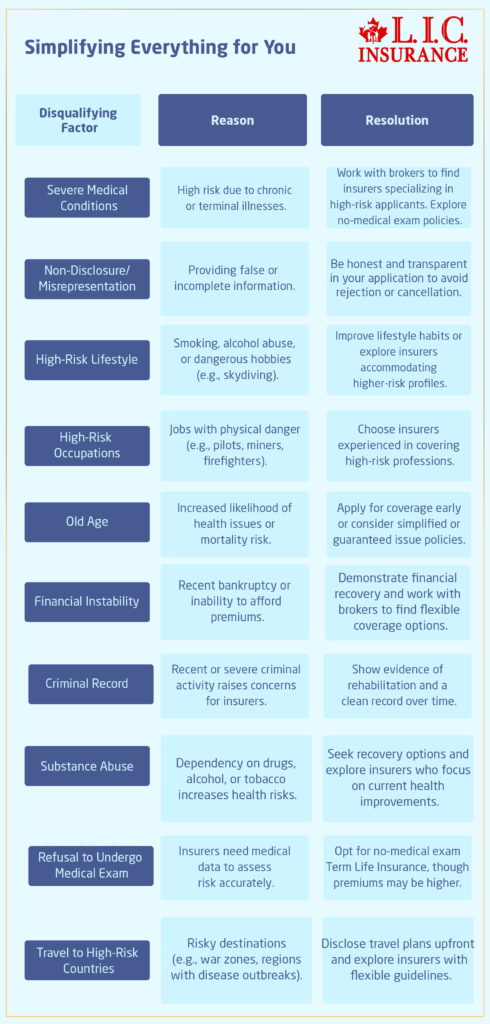
Life insurance coverage can provide crucial financial protection for liked ones, however those with pre-existing conditions often have a more difficult time getting a life insurance policy. Still, lots of medical conditions, consisting of diabetes, do not instantly disqualify an individual for insurance coverage. Most of the times, individuals with diabetes can still get life insurance coverage; they may have to pay more than a person without a pre-existing condition.
In this short article, we'll help describe: Insurance coverage service providers base premiums on the applicant's expected durability. Preexisting medical conditions can reduce life expectancy, which is why life insurance coverage for some diabetics tends to be costlier than it is for people without any preexisting conditions. Even when blood sugar level is well managed, the disease can potentially trigger problems, so it is a threat factor.
These include, however aren't restricted to: ObesityHeart diseaseHigh blood pressure (hypertension)HypertensionStrokeIssues with eyes, teeth, and other organsKidney disease or failureNeuropathyLimb amputationHowever, not all diabetics are the very same. Life insurance coverage companies rate candidate danger based on numerous factors, consisting of medical history, family medical history, existing health, age, and way of life (such as tobacco usage).
Candidates with well-managed diabetes and no issues may receive more beneficial policy terms. The life insurance company will usually have you complete a medical underwriting procedure to identify your risk to insure. This can consist of a questionnaire that inquires about your diabetes, in addition to the standard medical questions on the life insurance coverage application.
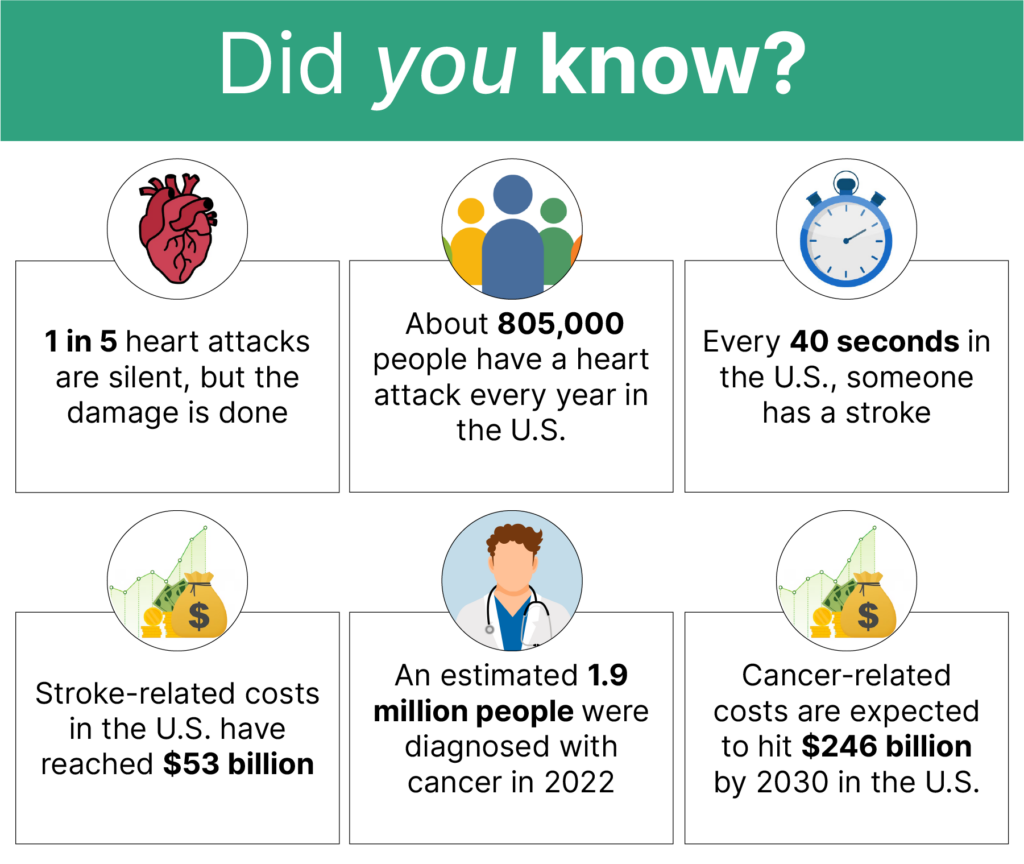
Life Insurance for Heart Attack SurvivorsInsulin therapy, which is typically needed for Type 1 diabetes and in some cases for Type 2 diabetes, may impact life insurance premiums. The insurance provider may likewise need medical records to confirm your health history. In addition, you will typically need to complete a physical examination (particularly if you're getting a high protection amount), and the life insurance company may likewise need a microalbumin test, which can help detect early signs of kidney damage.
Top Advantages of High Risk Life Insurance
full underwriting policies" listed below.) As part of the underwriting process, the life insurance coverage company will likewise inquire about the type of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. Individuals with each form of diabetes can still get life insurance coverage, but depending upon the base diagnosis, the application process might be more cumbersome, and the coverage offerings more limited.
When it happens later on in life, that implies it has actually impacted your body and health for a shorter length of time. Nevertheless, Type 1 diabetes is often diagnosed in kids or teens, making it a greater threat, and because of that, it is generally connected with greater premiums. Type 2 diabetes is often diagnosed at a later age than Type 1, so it has less time to impact the body.
If that is the case, and you have actually learned how to keep it under control with diet and exercise, you will likely qualify for the most cost effective rates (in relation to others with diabetes). However, even with Type 2 diabetes, people with diabetes-related problems and those who are insulin-dependent will find their life insurance coverage options more minimal and their premium costs greater due to higher danger.
In a lot of circumstances, gestational diabetes goes away after offering birth, however not always. In any case, pregnant females with gestational diabetes might wish to wait several months after delivering before requesting life insurance coverage. Presuming the diabetes goes away, it will then be much easier and less pricey to get a life insurance coverage policy.
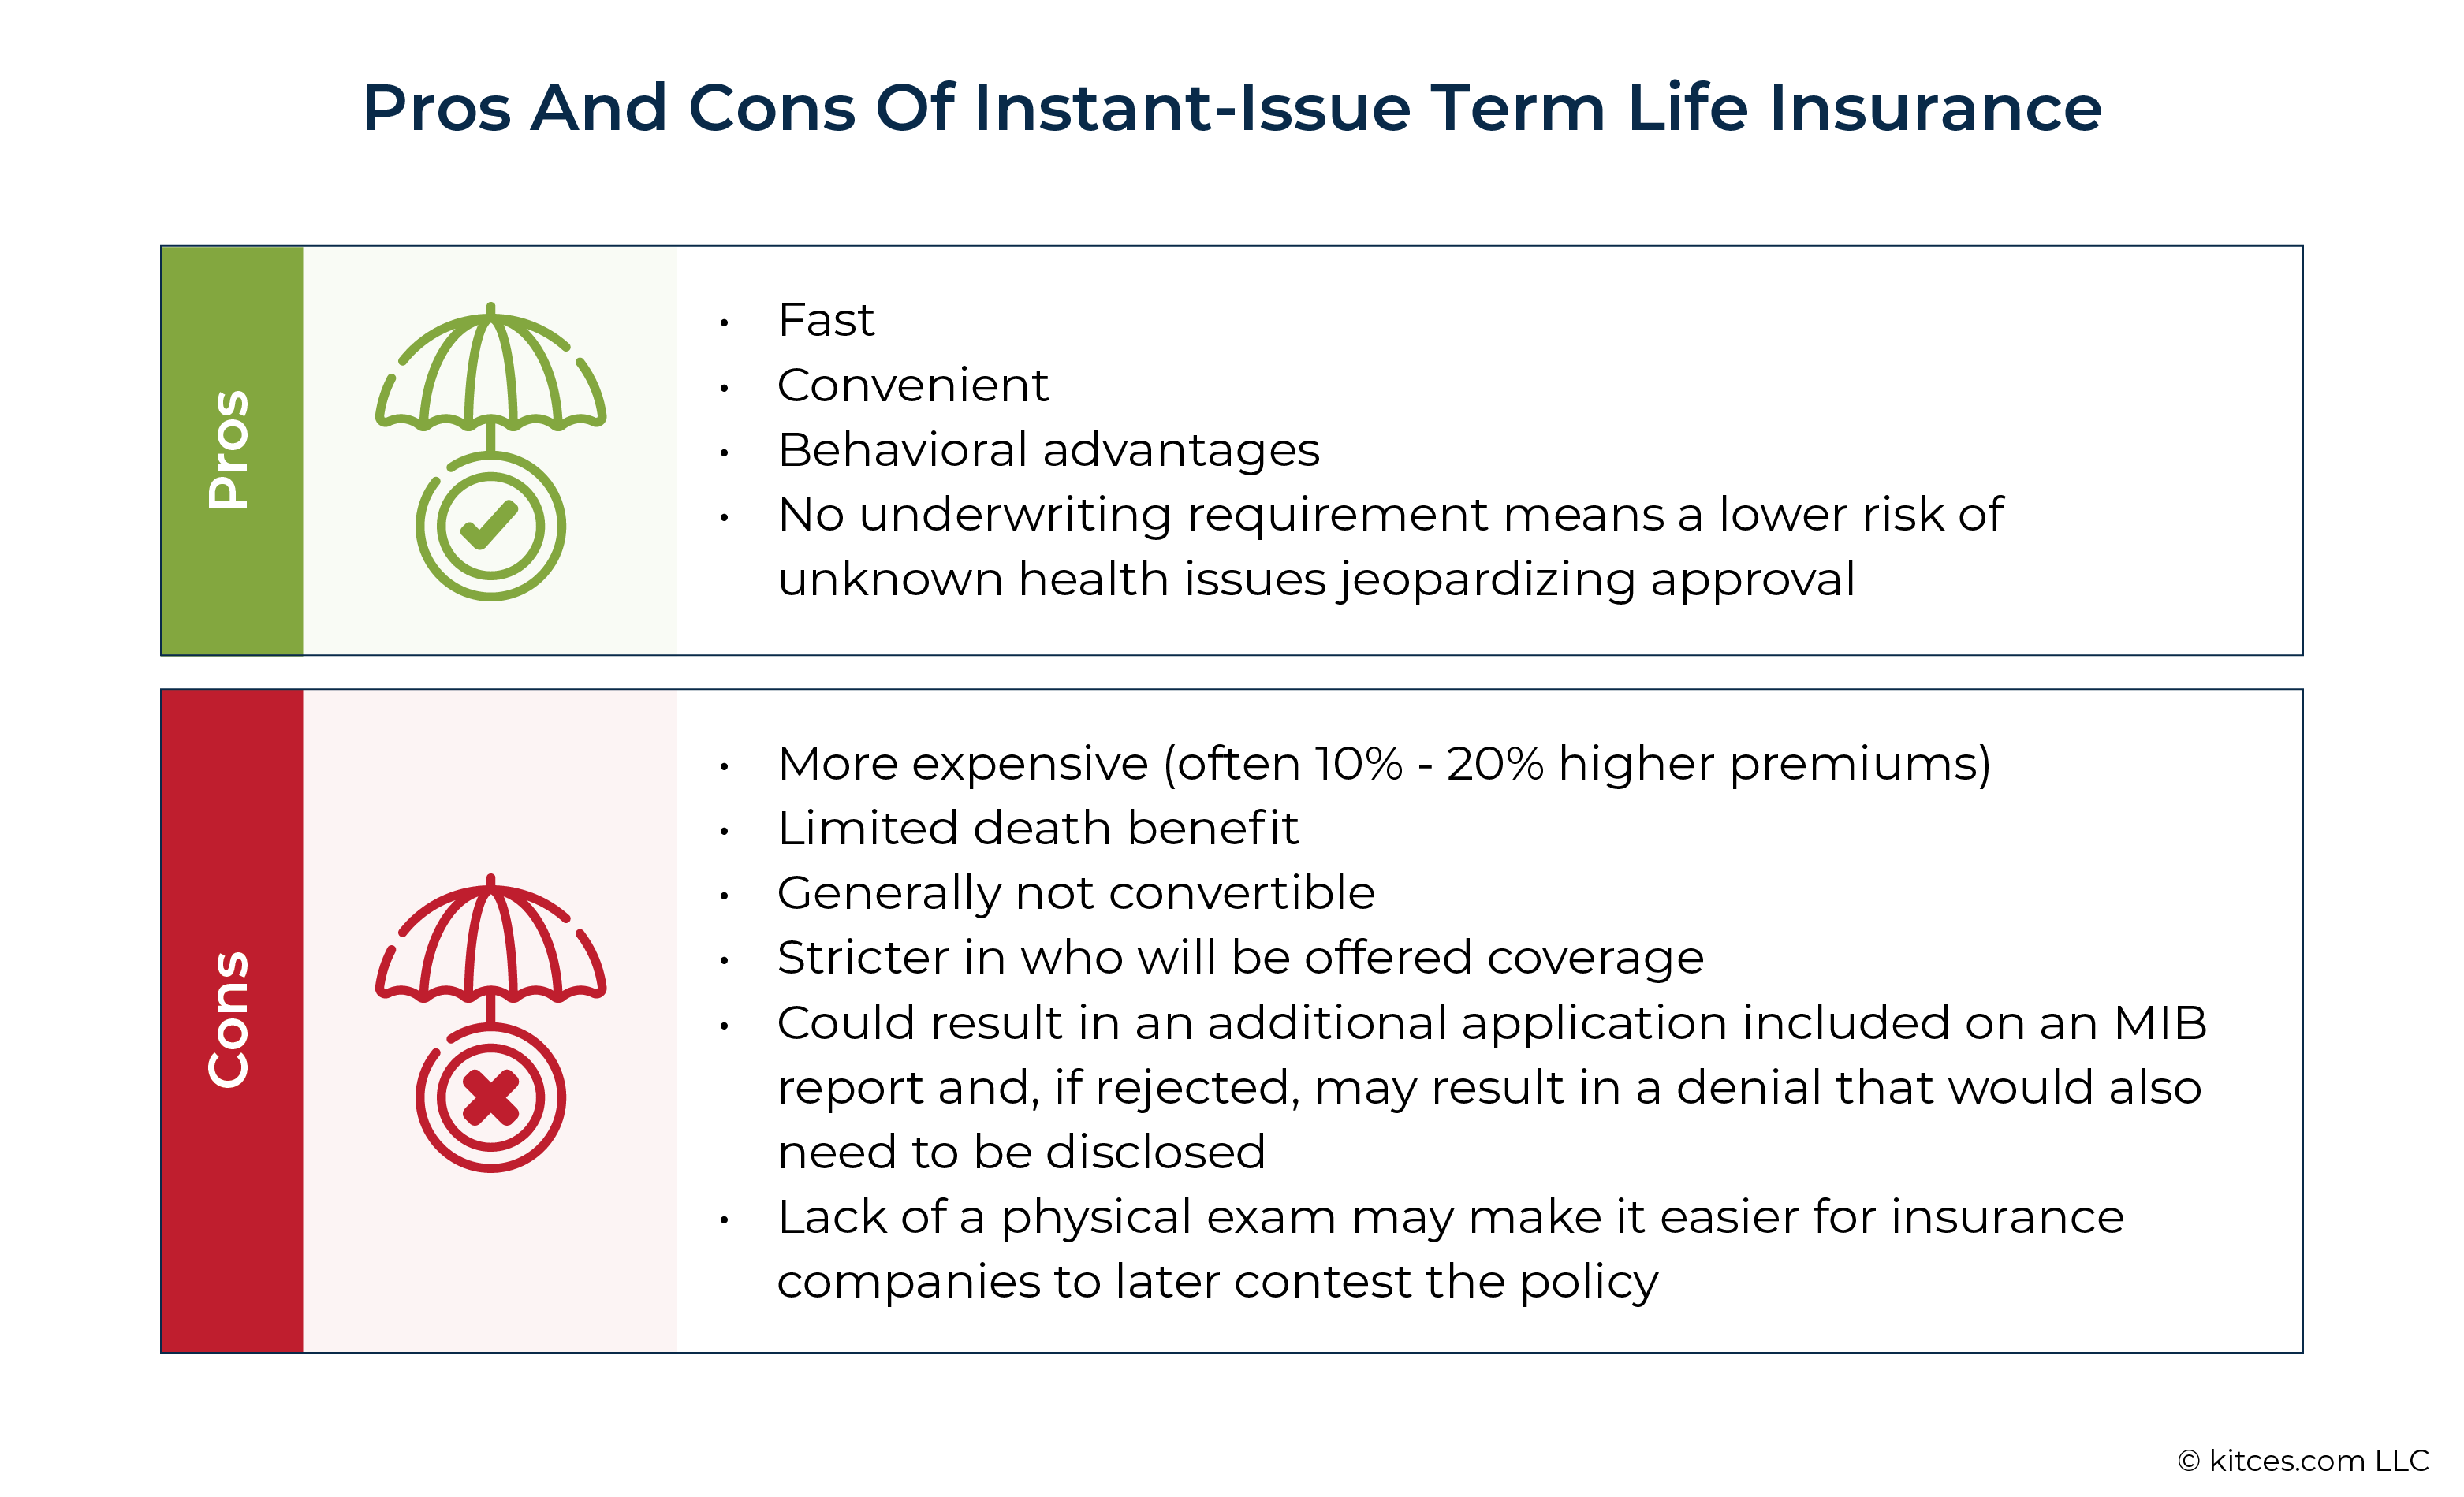
Numerous term policies can transform to long-term life insurance before the term ends without needing additional medical underwriting. If readily available, conversion can be an alternative to consider for people who bought a term life insurance coverage policy before they were diagnosed with diabetes and want to extend their coverage.
Life Insurance for HIV Positive Individuals
2,3 It may be best to purchase as much life insurance as you'll require (and can pay for) as quickly as possible, rather than wait to add more later. This is since life insurance coverage ends up being more expensive the older you get, and an underlying condition like diabetes will normally raise the expense even more.

Latest Posts

Managing Life Insurance for Modern Diabetic Applicants

2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips