All Categories
Featured
Managing Life Insurance for Modern Diabetic Applicants
2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips
Critical High Risk Travel Protection Basics for Global Trips
Table of Contents
Some plans pay a restricted quantity for an unexpected flare-up of a recognized condition (an "intense onset"). Where to purchase On the contrast, priced side by side. From the insurance company. Our 7 Corners evaluation covers the one we point individuals to. 7 Corners Travel Medical, the standalone plan we point people to, is offered to residents of the United States (New york city excepted) from 14 days old, covers journeys of 5 to 364 days, brings medical limitations as much as $1,000,000 for tourists under 65 ($ 100,000 for 65 to 79) with $500,000 of evacuation, offers deductibles from $0 to $1,000, and pays up to $50,000 for the first unexpected flare-up of a known condition for tourists under 65.
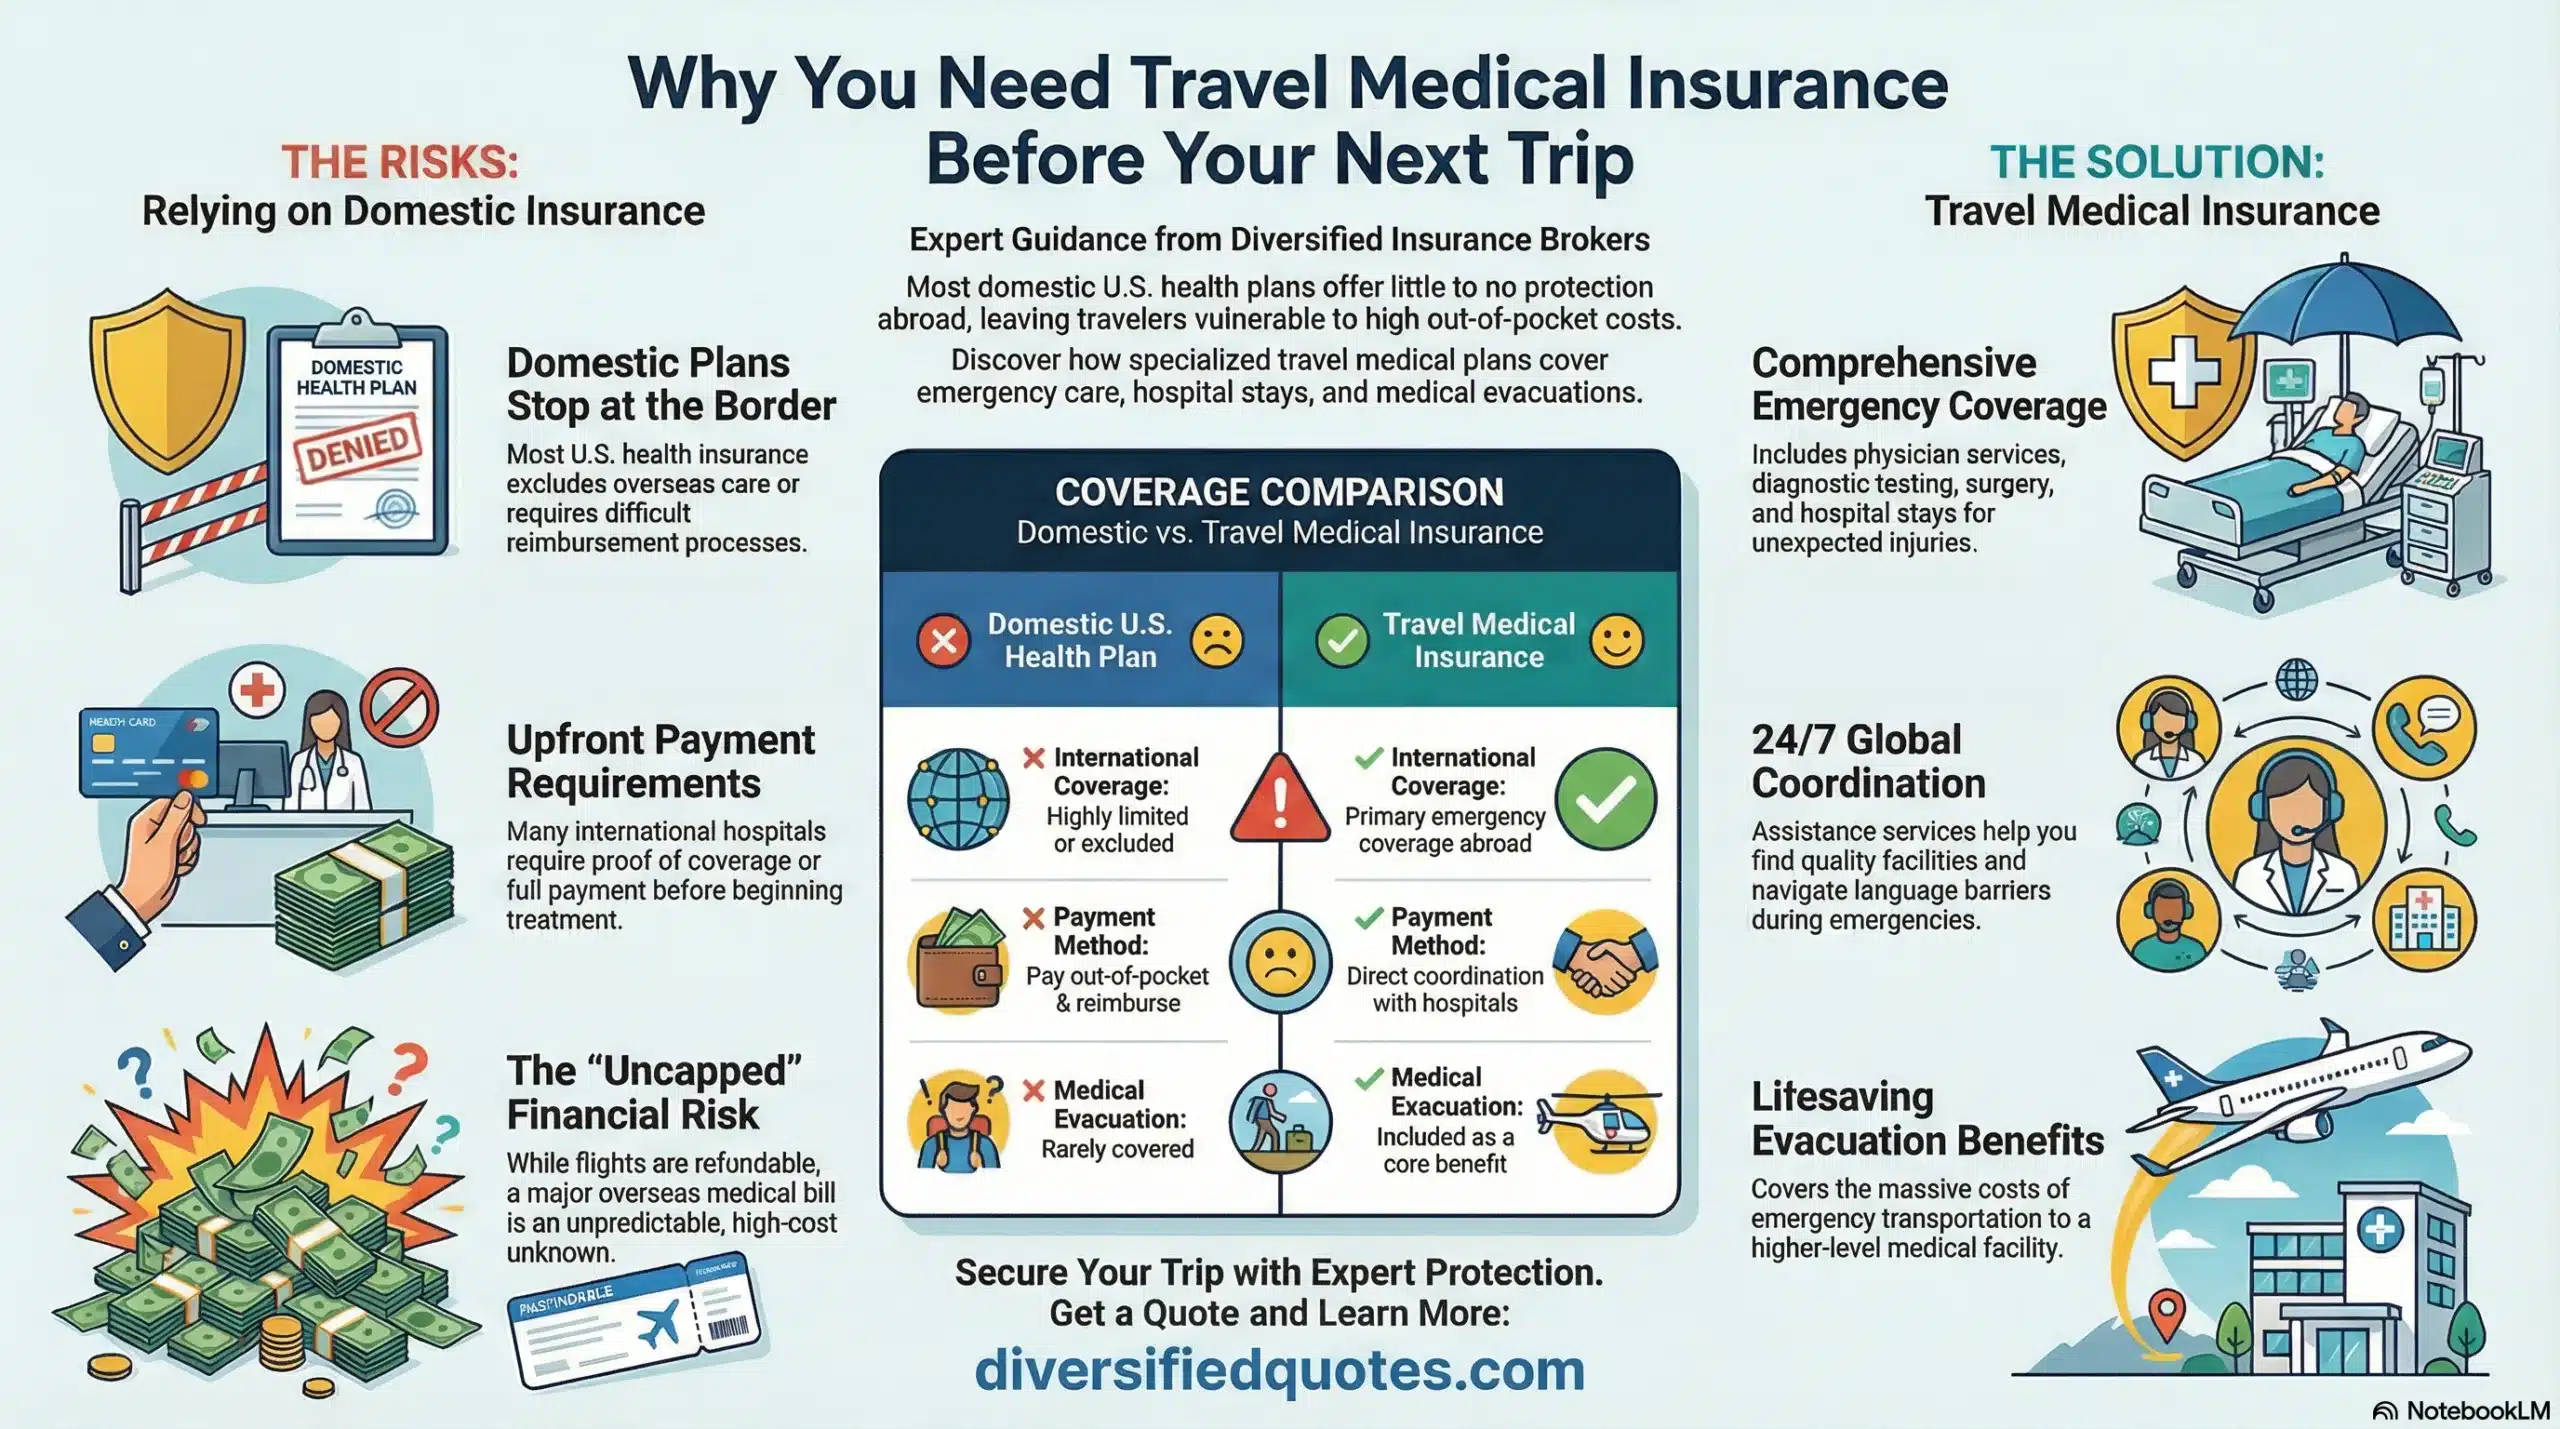
Those are the details to compare any standalone plan against. See every top strategy priced for your tripEnter your journey once and every top plan returns side by side, priced for your dates. Very same rate as purchasing direct.See strategies & ratesAbout one minute. Absolutely nothing to sign up for. Physician visits, hospital stays, surgical treatment, tests, X-rays and medication for an illness or injury that begins on the journey.
The ambulance, helicopter or air ambulance to get you to sufficient care, and the flight home with medical personnel if you need it, under the evacuation benefit. A 24-hour help line that finds the healthcare facility, talk with the medical professionals, organizes payment where it can, and keeps your family informed. Bringing a relative to your bedside and sending out kids home if you are hospitalized, on the majority of plans.
Set the two medical numbers initially, then look at cost. Standalone medical plans do not waive it.
Essential Medical Travel Insurance Strategies for Global Travelers
Some standalone strategies cut the medical limitation sharply at 65 and again at 80. A bundle strategy keeps the very same limit at every age; the cost goes up instead. Save the help number where a travel buddy can find it.
Travel medical insurance pays your physician and healthcare facility bills if you get ill or harmed on a journey, and pays to move you to a much better hospital and home if you need it. It comes two ways: as the medical benefit inside a routine travel insurance coverage package plan, or as a standalone plan that covers just the medical side.
The evacuation limit is different: $250,000 as a flooring, $500,000 or more for a cruise or a remote trip. The insurance company's assistance company can frequently organize to pay the health center directly for a large costs, especially an admission. For a smaller sized costs, a clinic check out or a prescription, you typically pay and declare it back with the invoices.
2026 Guidelines for HIV Life Insurance
Primary pays first, without any requirement to file with your health insurance coverage at home. Secondary pays what your other insurance coverage did not, which can imply filing with your health strategy initially and waiting. Abroad, where most health insurance pay absolutely nothing, secondary protection ends up paying the entire bill anyhow; primary is simply faster and involves less paperwork.
Some Medigap plans pay 80 percent of emergency care in the very first 60 days of a trip, after a $250 deductible, approximately a $50,000 lifetime limit, and never ever for evacuation. On a cruise, Medicare stops paying when the ship is more than six hours from an US port. Inside a bundle strategy, yes, if you buy within 2 week of your very first journey payment and guarantee whatever you have paid: 53 of the 54 plans we compare waive the exemption.
No. Inside a bundle plan it is consisted of in the rate. A standalone strategy is priced every day and by age and is often a couple of dollars a day, due to the fact that it carries no cancellation coverage. Some standalone plans can be bought after departure, and a couple of package strategies are built for it (Travel Guard Load N' Go and Berkshire Hathaway ExactCare Lite).
Current Criteria for HIV Positive Life Protection
Absolutely nothing purchased after you are already ill or hurt will cover that disease or injury. Outside the United States your health insurance coverage pays little or nothing and Medicare pays absolutely nothing, so the medical advantage in a travel insurance strategy is what pays the healthcare facility and the flight home. Set $100,000 of emergency medical as the flooring for a trip abroad and $250,000 or more for a cruise, a remote trip or a traveler over 65, set the evacuation number alongside it, and then compare plans on rate.

Latest Posts

Managing Life Insurance for Modern Diabetic Applicants

2026 Innovations in Impaired Risk Insurance Markets
Critical High Risk Travel Protection Basics for Global Trips